
When homeowners think about insurance, they often focus on how likely a claim is—but just as important is how expensive that claim can be. Some events happen more often but cost less, while others are rare yet financially devastating. So which home insurance claims are the most expensive: fire, flood, or theft?
Table Of Content
- Why Claim Severity Matters More Than Frequency
- Fire Damage Claims: The Costliest Covered Loss
- Why Fire Claims Cost So Much
- What Insurance Usually Covers
- Flood Damage Claims: Less Common, Often Financially Devastating
- Why Flood Claims Are So Severe
- The Coverage Gap
- Theft Claims: More Common, Usually Less Expensive
- Why Theft Claims Cost Less
- Commonly Stolen Items
- Comparing Fire, Flood, and Theft Claims
- Hidden Costs That Increase Claim Expenses
- How to Reduce the Risk of High-Cost Claims
- Are You Properly Insured for These Risks?
- Final Verdict: Which Claim Is Most Expensive?
This comprehensive guide breaks down average claim costs, why some losses are more severe than others, what insurance typically covers, and how homeowners can reduce risk and financial exposure.
Why Claim Severity Matters More Than Frequency
Not all claims affect your finances the same way. A single severe loss can:
- Exceed policy limits
- Trigger large out-of-pocket costs
- Increase premiums for years
- Force temporary relocation
Understanding high-cost claim risks helps homeowners choose better coverage and avoid underinsurance.
Fire Damage Claims: The Costliest Covered Loss
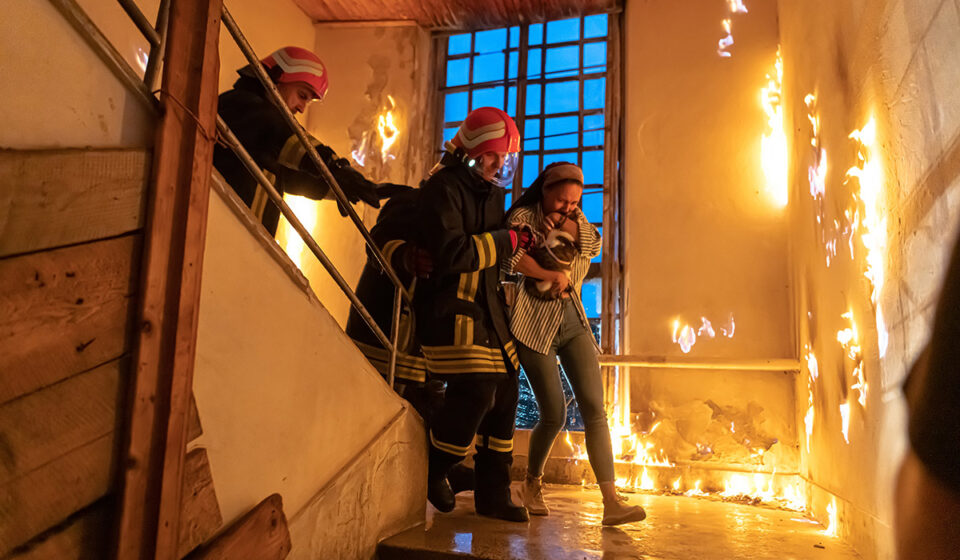
Fire claims are consistently the most expensive standard home insurance claims.
Why Fire Claims Cost So Much
- Structural damage often requires partial or full rebuilds
- Smoke and soot damage spread throughout the home
- Electrical, plumbing, and HVAC systems may need replacement
- Contents are frequently total losses
Even small fires can cause six-figure losses, especially when smoke damage affects the entire structure.
What Insurance Usually Covers
- Dwelling repairs or rebuilding
- Smoke and fire-damaged belongings
- Debris removal
- Temporary housing (Additional Living Expenses)
Fire is usually covered under standard homeowners insurance, making adequate dwelling limits critical.
Flood Damage Claims: Less Common, Often Financially Devastating
Flooding is one of the most misunderstood and underinsured risks.
Why Flood Claims Are So Severe
- Water saturates walls, floors, insulation, and foundations
- Mold remediation is expensive and time-sensitive
- Electrical and mechanical systems are often destroyed
- Repairs must meet updated building codes
Even shallow flooding can cause catastrophic damage, especially in finished basements and ground floors.
The Coverage Gap
Standard home insurance does not cover flood damage. Flood losses require:
- Separate flood insurance
- Government-backed or private flood policies
Without flood insurance, homeowners pay 100% out of pocket.
Theft Claims: More Common, Usually Less Expensive
Theft claims happen more frequently than fires or floods — but they tend to be far less costly.
Why Theft Claims Cost Less
- Losses are usually limited to personal property
- Structural damage is minimal or repairable
- Claims often involve partial losses
However, theft can still be financially painful if valuables are underinsured or not properly scheduled.
Commonly Stolen Items
- Electronics
- Jewelry
- Cash
- Firearms
- Luxury accessories
High-value items often require special coverage riders.
Comparing Fire, Flood, and Theft Claims
| Claim Type | Average Claim Severity | Covered by Standard Policy? | Financial Risk Level |
|---|---|---|---|
| Fire | Very High | ✅ Yes | 🔴 Highest |
| Flood | Extremely High | ❌ No (separate policy) | 🔴🔴 Highest without coverage |
| Theft | Low to Moderate | ✅ Yes | 🟡 Moderate |
Key insight: Flood claims are often the most financially devastating because many homeowners have no coverage at all.
Hidden Costs That Increase Claim Expenses
Regardless of claim type, costs rise due to:
- Code upgrade requirements
- Material and labor shortages
- Inflation in construction costs
- Extended displacement from the home
- Deductibles and policy limits
Underinsured homeowners feel these costs the most.
How to Reduce the Risk of High-Cost Claims
Smart prevention lowers both risk and insurance costs:
- Install smoke detectors and fire-resistant materials
- Maintain electrical and heating systems
- Use water leak sensors and automatic shutoff valves
- Elevate utilities in flood-prone areas
- Install security systems and reinforced locks
Many insurers offer discounts for proactive risk reduction.
Are You Properly Insured for These Risks?
Ask yourself:
- Is my dwelling coverage enough to fully rebuild today?
- Do I have flood insurance if I’m even near a flood zone?
- Are valuables properly scheduled?
- Would I afford my deductible in a major loss?
Insurance should be reviewed annually, especially after renovations or rising construction costs.
Final Verdict: Which Claim Is Most Expensive?
- Fire is the most expensive covered home insurance claim
- Flood is the most financially devastating uncovered loss
- Theft is common but usually manageable with proper coverage
The real danger isn’t which claim happens — it’s being unprepared when it does.